Investing in the Infrastructure Behind the Infrastructure
Private market investments in infrastructure are broadening in scope to expand beyond ownership of physical assets into the businesses that build, equip, protect, operate, maintain and digitize them. The opportunity set is expanding alongside a rapid growth in the larger infrastructure market, which set fundraising records in 2025 and will require an estimated $106 trillion of cumulative investments through 2040, according to McKinsey.1 The scale of the sector’s build-out is creating a large addressable market, and investments are being underwritten through a different lens than prior years.
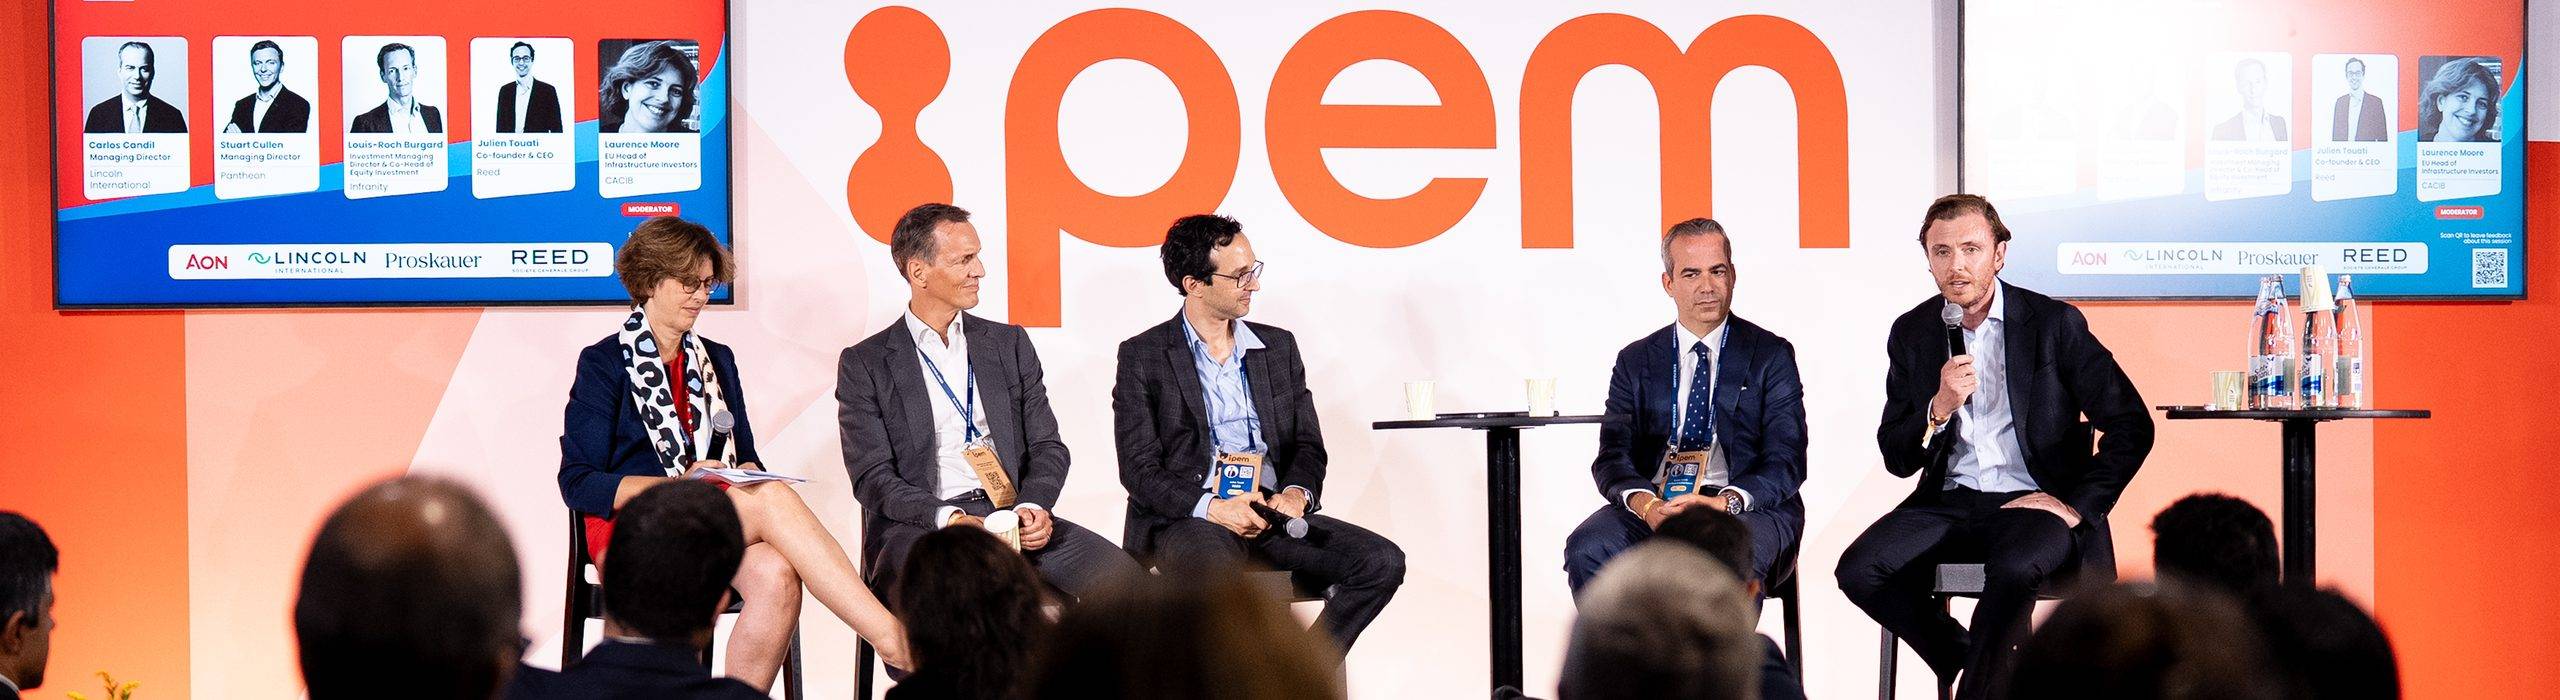
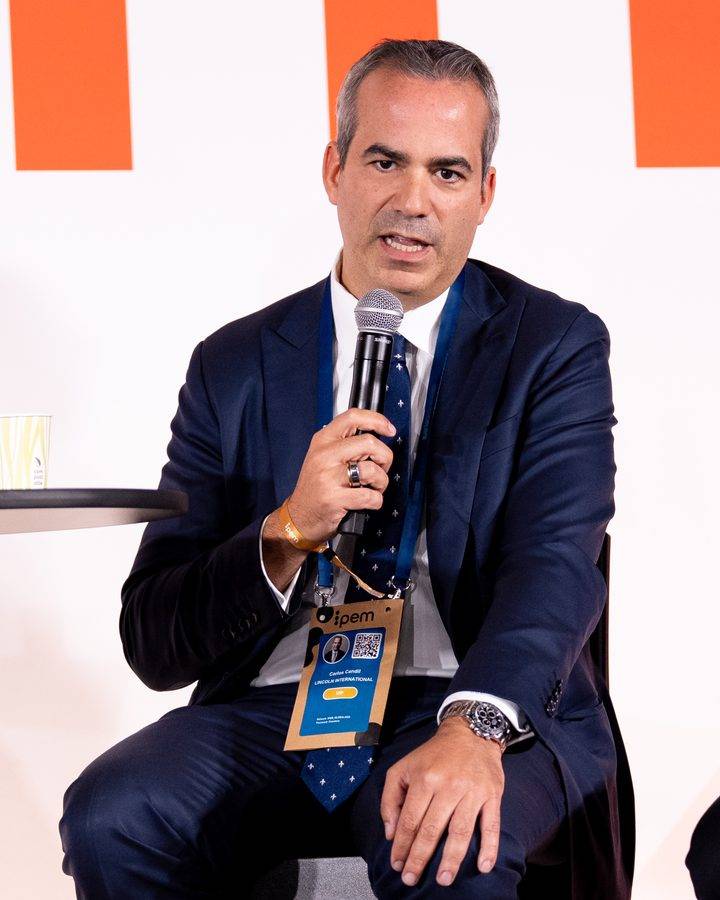
Lincoln International was pleased to speak at IPEM Global 2026 in September 2026, where the team met with private market investors and fund managers from around the world. In the article below, Lincoln’s experts unpack the opportunities surrounding the traditional infrastructure market and the themes driving today’s markets and sponsor conversations.
Summary
- Lincoln International unpacks the opportunities surrounding infrastructure investments and the themes driving today’s private market investments in the infrastructure market.
- Sign up to receive Lincoln's perspectives


Where the Opportunities Sit in Infrastructure
Physical infrastructure appeals to a wide base of investors thanks to its core essentiality, which lends itself to recurring and repeat revenues, as well as customer stickiness and limited replaceability. Strong assets are also exposed to a diverse range of end markets, as well as differentiated by a high installed base, proprietary IP, industry certifications, scarce technical capabilities around the market and strong cash conversion.
As the opportunity set expands beyond physical infrastructure assets, the infrastructure behind infrastructure with the highest investor interest falls into four broad buckets. Across each one, the critical question for sponsors is if an asset is simply exposed to the infrastructure end market or if the asset offers the same benefits seen in traditional infrastructure. These models can offer higher growth and better capital efficiency than traditional core infrastructure, but they also introduce operational, labor, working-capital and project risks that need to be underwritten honestly.
As with any investment opportunity, not all assets in the buckets above are strong investments. Sponsors must consider the risks inherent in infrastructure that carry over to the broadened scope of investments. Similar to infrastructure assets, project-based revenue remains difficult to predict, as are thematic assumptions that fail to materialize within a two-year business plan.
Beyond these, competitive retendering, labor intensity without pricing power, customer concentration and working-capital drag are all factors for sponsors to consider when assessing an infrastructure-exposed asset. Assets that are overbuilt, possess high capital expenditure and leverage or lack defensible differentiators should not be considered an “infrastructure” investment.
Market Themes and M&A Takeaways
Assets in the four outlined buckets are receiving attention from infrastructure funds, private equity and strategic acquirers all at the same time. As LPs are increasingly cautious with shifting market conditions, value creation is emphasized alongside the return spectrum moving up. The eventual purchase will be underwritten through a different lens depending on the acquirer type, but the convergence itself is evidence that the boundary between infrastructure and private equity is moving.
The strongest themes in today’s market are consistent across sponsor type:
-
Grid supply and electrification
An estimated $3.4 trillion will be invested in global energy in 2026, with roughly $2.2 trillion dedicated to electrification and clean energy-related areas. Approximately $400 billion is invested annually into the global energy grid today, which will need to rise by more than 50% before 2030 to meet current demand trends.
-
Data center power and resilience
The European Commission expects data center capacity in the EU to more than double from 2025 to 2030, from 12 GW to approximately 28 GW. Providing enough energy on a reliable basis will require a massive influx of investment and innovation.
-
Maintenance and aging infrastructure
Roughly 40% of Europe’s distribution grids are more than 40 years old, and more than 2,500 GW of renewable generation, storage and large-load projects, including data centers, are stalled in grid connection queues globally. In addition to the outdated energy grid, civil infrastructure is also showing its age, with a large amount of Europe’s critical civil infrastructure reaching the end of its service life.
Lincoln’s Relevant Transactions
Lincoln has advised on transactions across each of these areas, providing first-hand insight into how infrastructure investors, private equity sponsors and strategic buyers assess these business models. The team brings deep sector insights and unparalleled valuations benchmarking capabilities to each deal.
 ASTPContracted and operational services
 BRUSHSpecialist engineering and products
 BUKOContracted and operational services
 IORContracted and operational services
 Irth SolutionsMission-critical software
 MacLean Power SystemsSpecialist engineering and products
 WCCTVEquipment-plus-service and rental models
 Zwart TechniekSpecialist engineering and products
Looking Ahead with Lincoln
More and more, the best opportunities for infrastructure investments sit outside of the physical assets. The infrastructure label should be earned by the quality of the revenue model, not by the logo of the customer.
1 McKinsey & Company, “Infrastructure: Investing to support global growth,” March 23, 2026.